 A Message From Profits Run If you still haven't downloaded my "Safe Trade Options Formula" book... ...please take a few seconds and download it right now before your new temporary download link expires. I eventually plan to charge for this book, so do yourself a favor and download it now... That way, no matter how much it is in the future, you'll have a copy on your computer already. Make sense? FREE: Safe Trade Options Formula << Download Now Good Trading,
Bill Poulos p.s. Go here to save a copy of my "Safe Trade Options Formula" book to your computer before I start charging for it.
Featured News from MarketBeat
3M's Legal Troubles Are Fading. Is the Best Part of Its Rally Still Ahead?By Thomas Hughes. First Published: 10/21/2026. 
Key Points
- 3M's Q3 results showed accelerating earnings and margin growth, with shares surging more than 5% following the report.
- An expanded Amazon partnership for optical connectivity solutions strengthens 3M's role in the data center supply chain and reduces long-term growth risk.
- 3M faces ongoing legal risks from PFAS-related claims, including an Australian lawsuit seeking more than $2 billion in damages.
- Special Report: Ready to give options a try? Your first trade (Ticker included) -INSIDE
3M (NYSE: MMM) stock has been in recovery mode since early 2024, when the company began emerging from legacy issues, including liabilities related to its decades of producing PFAS, the so-called “forever chemicals” linked to environmental contamination and health concerns, and the class-action lawsuits that followed. These issues continue to affect results, but their impact is fading and is already reflected in the outlook. The 2026 narrative is that the company will sustain growth, widen margins and return ample capital to investors while strengthening its outlook. Key takeaways from 3M's Q3 report include numerous product wins across industries, highlighting the quality and diversity of its revenue streams. These wins include an expanded partnership with Amazon (NASDAQ: AMZN), which is relying on 3M for optical connectivity solutions and expects to spend billions on products over the next few years. While the deal includes potential dilution, with Amazon receiving warrants for approximately 1% of 3M stock, it also makes 3M a critical part of the data center supply chain and de-risks its long-term growth outlook.
Business is improving and legacy issues are fading, allowing 3M’s stock price to recover. MMM shares surged more than 5% after the Q3 report and are trading near long-term highs, putting them on track to set fresh highs before year-end. A move to new highs would confirm the pivot and set the stock up to retest its record highs in the coming year. 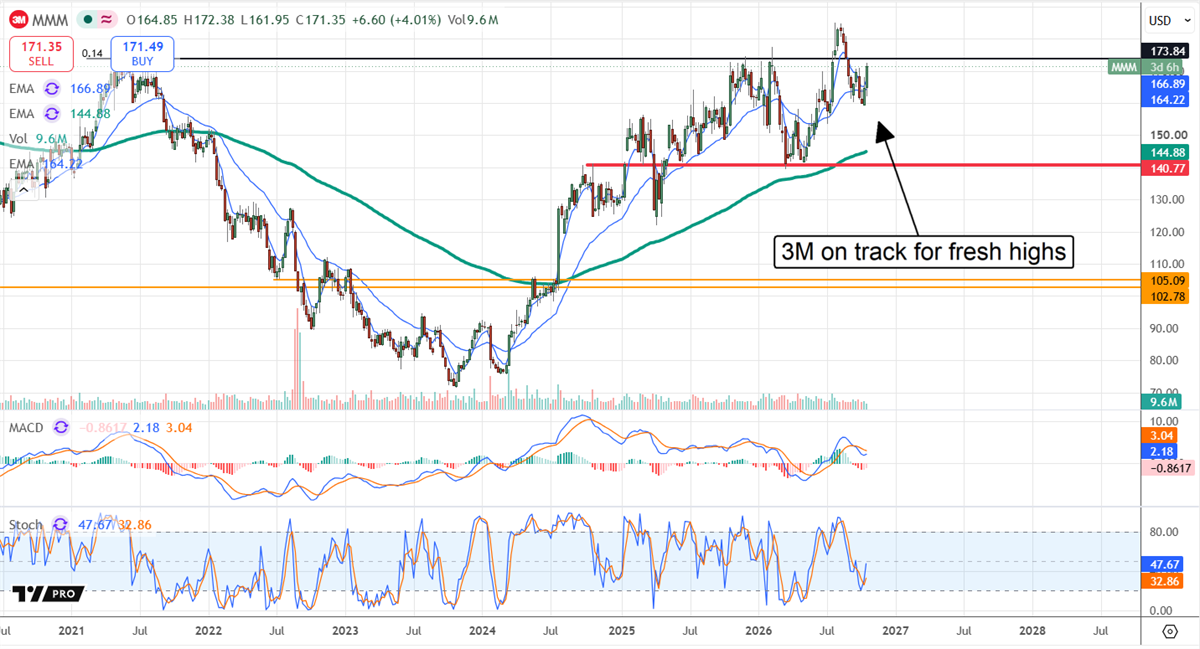
3M Grows and Widens Margins in Q3, Strengthening Capital Return Outlook3M had a decent quarter, although it continues to contend with the impact of lost PFAS business. Headline growth came in at 1%, or 4.8% when adjusted for PFAS, underpinned by 3.3% organic growth and 0.9% growth from acquisitions. By segment, Safety and Industrial was strongest, growing 9.1%. That performance was offset by a smaller 0.4% increase in Transportation and Electronics and a 0.4% decline in Consumer. Regionally, Latin America was strongest, with growth of 11.1%, followed by 9% domestic growth. These gains were offset by contraction in the rest of the world. Margin was the real strength, with adjusted operating margin expanding by 110 basis points and earnings growth accelerating. Adjusted earnings per share grew 12% versus the 4.8% top-line advance, exceeding MarketBeat’s reported consensus by 12 cents. More importantly, free cash flow improved significantly to approximately $1.2 billion, more than sufficient to maintain balance sheet health while returning capital to shareholders and investing in growth. Capital returns are central to the stock price outlook, including dividends, dividend growth and share buybacks. The dividend yield is down from prior highs but remains attractive at about 1.8%. It is appropriately sized to cash flow, with shares near long-term highs. More importantly, the dividend is viewed as safe, with a payout ratio below 35% of earnings guidance and sufficient cash flow available to support share buybacks. Collectively, capital returns amounted to 50% of quarterly free cash flow, with buybacks reducing the share count by an average of 2.85% during the quarter and 2.55% year to date. 3M Is on Track for Sustainable Improvement in 20273M’s balance sheet is healthy and stable but thin on equity, with the long-term debt-to-equity ratio at approximately 4x due to legacy issues, restructuring and the company's commitment to capital returns. The potential catalyst is debt reduction. If free cash flow remains robust, 3M can pay down debt over the coming quarters, rebuilding equity while buybacks continue to reduce the share count. This gives shareholders a dual lever for value creation and gives institutions more reason to own the stock. Analyst sentiment trends—including downgrades and price target reductions—reflect some caution, but they are offset by the overall bullish trend. MarketBeat data shows that analyst coverage is rising, with 15 analysts covering the stock. Consensus is Hold, although the bias is bullish. Price targets have also been rising, with the consensus projecting modest upside as of late October and the trend pointing toward record levels. The likely outcome is that upcoming results will affirm the business recovery, keeping analysts bullish and price targets moving higher. Institutional Support Remains Solid, Limiting 3M’s Downside RiskInstitutional activity also reflects optimism about 3M’s long-term outlook. The group owns 65% of the shares, has maintained a steady position despite the company’s struggles and continues to accumulate shares. Activity is down compared with prior years—merely a trickle—but it is a bullish trickle that may strengthen given the business recovery. Short sellers do not appear to pose a significant risk at this time, with short interest below 2% of the float. 3M’s biggest risks are legal, including unsettled and disputed claims such as a PFAS settlement in Australia. The government is aggressively seeking more than $2 billion in damages, and the outcome remains uncertain. 3M has a solid case and may ultimately pay a much smaller amount. Catalysts include guidance. The company raised its Q4 targets, expects full-year earnings well above consensus and remains cautious in its estimates. Headwinds or not, data centers are being built and need materials that only 3M can make. . |


0 Comments:
Post a Comment
<< Home