 A Message From Banyan Hill Publishing Dear Reader, Three days into his second term, President Trump signed Executive Order 14178. The press barely noticed. But buried inside was the legal green light for the boldest change to American money in over 100 years. And it’s finally about to take effect. I’ve spent months digging into what this order actually means.
What I found could send shockwaves through the financial system: Musk — with the quiet cooperation of the U.S. Treasury — is now positioned to “reboot” the dollar itself. Not someday. Potentially as soon as January 18. And it could all come down to one vote — led by Trump’s own Treasury Secretary. When it happens, life as we know it could change… and investors who saw it coming could make a fortune. Go here for the full story. Regards, 
Ian King
Chief Strategist, Strategic Fortunes
Additional Reading from MarketBeat.com
Why Sticky Services Inflation Could Lift These 3 StocksSubmitted by Nathan Reiff. Article Published: 10/7/2026. 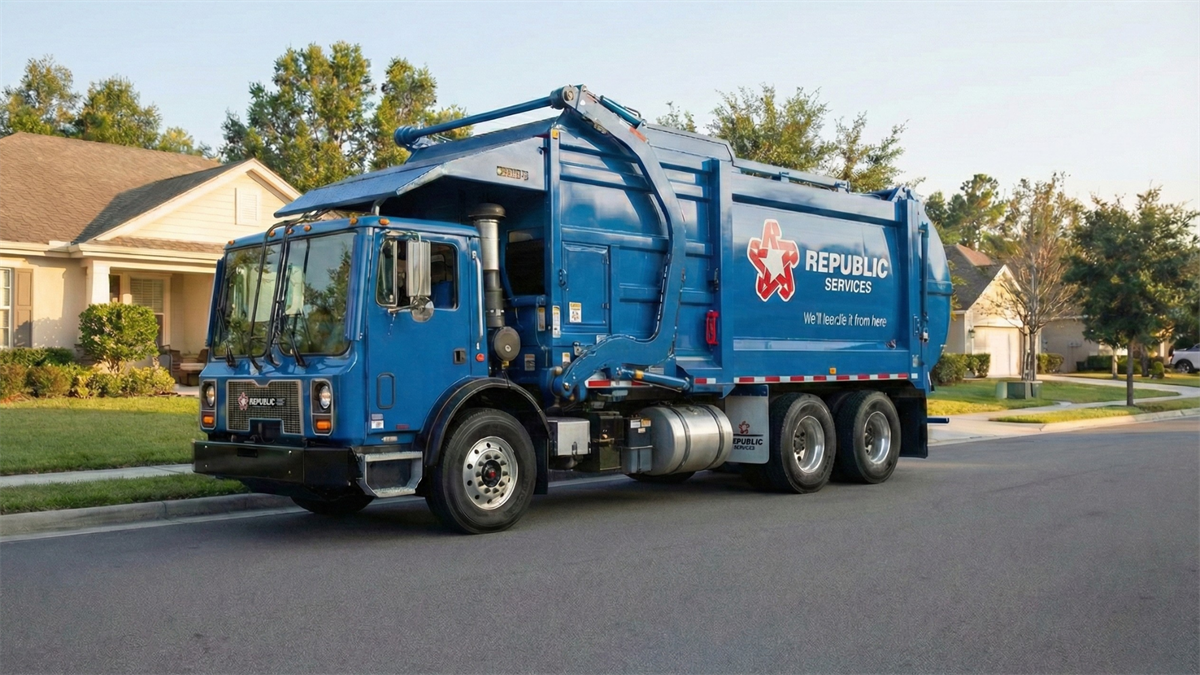
Key Points
- Services prices, tied to long-term contracts, wages, and rents, represent an often-overlooked inflation driver that could benefit certain companies.
- Republic Services uses CPI-linked long-term contracts to boost revenue and raised full-year guidance, with analysts projecting about 14% share upside.
- CoStar Group and CBRE Group offer differentiated commercial real estate exposure, with analysts projecting roughly 45% and 38% upside, respectively.
- Special Report: Do NOT Buy SpaceX – Do This Instead
Energy price shocks and tariffs are two of the most discussed factors driving inflation today, but investors can easily overlook another key catalyst: service prices. The services sector's breadth makes it particularly relevant when prices are rising overall, and a handful of vital but often overlooked offerings are seeing increased pricing power alongside sustained commercial activity. Companies operating in the waste management and commercial real estate industries could benefit from higher prices that remain stickier than those in the energy sector. After all, energy prices can drop suddenly when supply improves, while service prices tend to be tied to longer-term contracts, wages, rents, and other factors. The three companies below provide different ways to gain exposure to the services industry, but all could benefit from the current environment. Republic's Business Model Rewards Inflation With Long-Term Contract Boosts
Republic Services Inc. (NYSE: RSG) is one of the largest providers of solid waste management services in the country. This defensive industry is typically characterized by recurring demand, thanks to long-term city and commercial contracts. These contracts often include annual price increases tied to the Consumer Price Index (CPI). As contract rates reset higher, Republic's revenue can rise—even while the number of customers or the volume of waste collected remains essentially flat. This gives investors a significant advantage over some cyclical commodity producers, which require surges in physical volumes to capitalize on higher prices. Another advantage for Republic in the current climate is that it can benefit from elevated prices over the longer term, even if those prices do not remain high, thanks to its long-term contracts. Last quarter, the company increased revenue by 4.6% year over year (YOY) while maintaining its EBITDA margin. This prompted management to raise the company's full-year guidance, including an expectation that adjusted free cash flow could reach as much as $2.58 billion. This sizable cash flow will help the company continue its aggressive acquisition strategy. Analysts see significant upside for Republic, anticipating that shares could climb by 14%. Investors also receive the added benefit of a stable dividend yielding 1.25%. CoStar's Commercial Real Estate Data May Grow When Services Demand Is StrongA combination of higher mortgage rates, squeezed consumers, and elevated prices has introduced new volatility to the residential real estate market. However, commercial real estate remains differentiated, and CoStar Group Inc. (NASDAQ: CSGP) offers a unique play in this part of the industry. CoStar offers data, analytics, and marketplace platforms for commercial real estate, positioning the company to benefit as transaction activity across various parts of the market picks up. To the extent that persistent inflation in the services environment indicates resilient demand, it may also suggest that business expansion, leasing activity, and demand for commercial real estate information could increase. The company's last earnings report was mixed. Although earnings beat analyst estimates, revenue growth fell somewhat short of expectations despite rising more than 18% YOY. Crucially, profitability is improving, and adjusted EBITDA more than doubled YOY during the period. In addition to CoStar's core commercial real estate business, the company has a growing residential marketplace. Despite challenges in the residential market, CoStar's Homes.com platform is scaling and provides an important way for the company to build exposure to another part of the industry. Down about 59% year to date (YTD), CSGP shares are expected by analysts to rise by about 45% and reach the consensus price target of $40.11. A Broad Commercial Real Estate Play Benefiting From the Needs of the Services IndustryCBRE Group Inc. (NYSE: CBRE) is a broad commercial real estate services firm offering property management, leasing, capital markets, and more. This distinguishes it from CoStar, even as it can benefit from some of the same growth drivers. Services-sector businesses require space, advisers, leasing, and other products that CBRE offers. In this way, the company can directly benefit from growth in the services sector. CBRE's advantage is that it does not require a particular property type or transaction category to generate top-line benefits. The company has a massive geographic footprint and offers a wide range of services, making it well diversified. At the same time, CBRE shares are down only about 19% YTD, less than CoStar. Wall Street analysts still see 38% upside, with seven Buy ratings compared with a single Hold.
This ad is sent on behalf of Banyan Hill Publishing.
This ad is sent on behalf of Banyan Hill Publishing.
. |


0 Comments:
Post a Comment
<< Home