 A Message From Weiss Ratings Dear Reader, A market legend is predicting a monumental and historic event (which could unfold in as little as 24 hours) is about to hit America. He says it will change the fortunes of average Americans forever. Not just in the stock market. But how they bank, how they are paid from their jobs, how their insurance policies work and how their businesses operate every single day. Keep in mind this legend has made some shocking predictions over 55 years. And the crazy thing is the accuracy of his predictions are usually dead-on target. He predicted the double-digit inflation of the 1970s. The collapse of the S&L banks and the "Black Monday" stock crash in the 1980s. The dot-com collapse and the implosion of Fannie Mae, Bear Stearns and Lehman Brothers in the 2000s. He's testified before Congress. And The New York Times has credited him as being "the first to see the dangers." This goes deeper than the headlines about the stock market and recent highs. This is bigger than AI, bigger than the midterms, bigger than oil prices and bigger than what's happening in the Middle East. And it's already impacting thousands of Americans. This legend has just issued a free video to warn the public. For most, it will be a rude awakening. We want as many Americans as possible to see this. This legend explains exactly what's happening along with a few simple steps to protect yourself, and even come out ahead. Get Ready for an Ominous New Day in America Sincerely, Eliza Lasky
Weiss Advocate
Today's Featured Article
What the Sandals Deal Means for Royal Caribbean's Next Leg of Growth?Written by Sam Quirke. First Published: 10/12/2026. 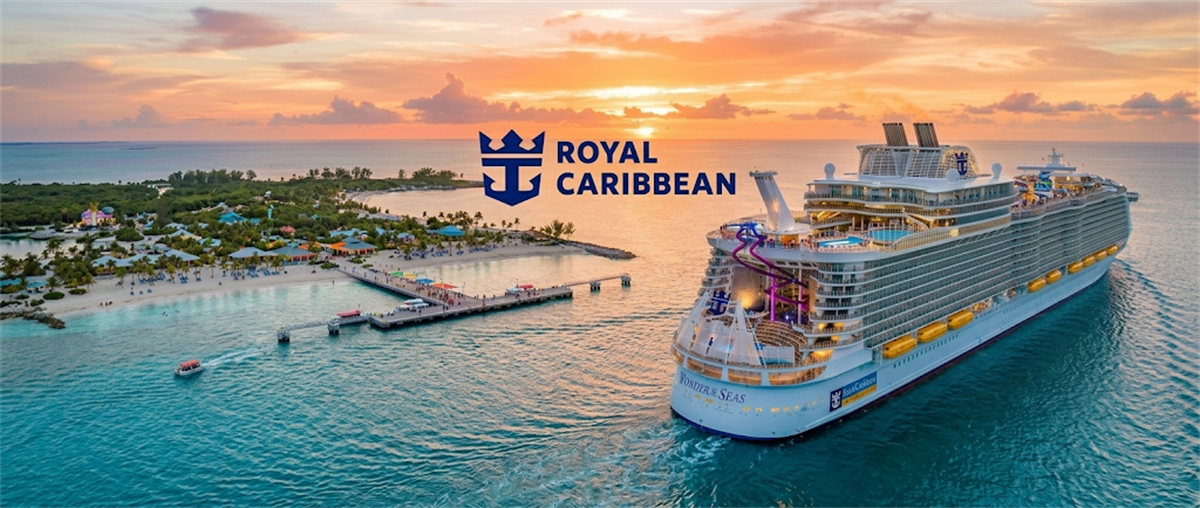
Key Points
- Royal Caribbean agreed to pay about $3 billion for a 50% stake in the company behind Sandals resorts, pushing shares up roughly 25% in two weeks.
- The company's core cruise business remains strong, with robust 2027 demand, elevated bookings, firmer pricing power, and growing onboard spending supporting earnings.
- Analysts including Jefferies, Barclays, and Citigroup remain bullish despite risks from debt financing the deal and potential increases in fuel costs.
- Special Report: The Healthcare AI Trend Wall Street Is Watching Closely
Royal Caribbean Cruises Ltd. (NYSE: RCL) has rarely looked more ambitious. The cruise giant has agreed to pay around $3 billion for a half-share in the company behind Sandals, the famous all-inclusive Caribbean resort brand. It is a bold move beyond the open water and onto dry land. Investors have cheered the step. Although RCL shares are still roughly flat for the year, they have surged about 25% in the two weeks since the deal was announced, trading near $280.
After an initial wobble as the market digested the price tag, the mood turned firmly optimistic, helped by a wave of supportive analyst commentary. So, what does this deal really mean for Royal Caribbean's next phase of growth? Is buying into the resort business a shrewd way to extend an already booming franchise, or an expensive distraction that piles on debt at an uncertain moment? Why the Deal Makes SenseThe logic behind the move is more compelling than it might first appear. Rather than simply adding more ships, Royal Caribbean is building a broader vacation empire that spans cruises, private destinations, loyalty programs and, now, land-based resorts. The appeal lies in the connections between them. A Sandals guest could be tempted to take a cruise, while a loyal cruiser could be encouraged to book a resort stay. In turn, the entire ecosystem could support a more frequent, higher-spending customer relationship. It also deepens the company's position in its most important market, the Caribbean, where demand remains particularly strong. The deal offers a tangible financial sweetener as well. Jefferies, which upgraded the stock to a Buy, estimates the venture could add around $159 million to earnings in 2027, or roughly 59 cents per share. For a deal that is not expected to close until early next year, that would be an impressively quick contribution to the bottom line. A Business Already Sailing WellCrucially, this expansion is happening from a position of strength. Royal Caribbean's underlying cruise business is in fine health, with management describing demand for 2027 as very strong and bookings already running at elevated levels. Better still, that demand is giving Royal Caribbean real pricing power. The company says it can increasingly raise prices on last-minute bookings rather than slash them to fill cabins, a telling sign that demand for its cruises is outstripping the supply of berths. Nor is the company wholly reliant on ticket prices. A growing share of revenue now comes from what guests spend once aboard, including drinks and shore excursions, giving Royal Caribbean another lever to pull even when fares rise only modestly. This combination of full ships, firmer pricing and higher onboard spending has Wall Street upbeat. A Few Clouds on the HorizonFor all the optimism, a dose of caution is sensible, and the biggest question mark hangs over the debt behind the Sandals deal. The $3 billion stake is being funded with borrowed money. While the exact terms have not been disclosed, taking on fresh debt inevitably raises interest costs and leaves less room for maneuver if conditions sour. There is the ever-present issue of fuel, as well. Rising crude prices are a real threat to a business that burns so much fuel. Although strong pricing and onboard spending should help absorb the hit, that cushion may not be enough if fuel costs climb sharply from here. The deal itself must also prove its worth. A $3 billion outlay sets a high bar, and the venture will need to deliver the promised earnings without consuming more cash or management attention than expected. With a 50% stake, Royal Caribbean shares both the rewards and the risks without holding full control. Can the Rally Keep Rolling?Looking ahead, it is hard not to view Royal Caribbean as an attractive way to play the enduring strength of the cruise market, with the Sandals deal adding a fresh and potentially lucrative string to its bow. The core business is thriving, demand is robust, and the company has found a new avenue for growth while its existing business remains strong. Wall Street largely agrees. The stock carries a MarketBeat Moderate Buy consensus rating, and enthusiasm has only grown since the deal was announced. This week, Barclays reiterated an Overweight rating with a $337 price target, implying around 20% upside from current levels and a return to the top of the stock's recent range. At the same time, Citigroup reaffirmed its own Buy rating the week before. Yes, the debt and fuel risks are real, and a $3 billion bet is never without danger. But Royal Caribbean has given the market plenty to be excited about. For investors who believe the cruise boom has further to sail, the recent rally could easily have another leg in it.
11780 US Highway 1,
Palm Beach Gardens, FL 33408-3080
Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved.
. |


0 Comments:
Post a Comment
<< Home