 A Message From Brownstone Research Dear Reader, Do you hold any of these AI stocks? 
Wall Street insider Jason Bodner — the man who called Nvidia at $4.50 — says today’s AI stocks are about to hit a wall. And a completely different group of AI firms… names Wall Street is starting to ignore… are about to take off. This has nothing to do with SpaceX… A new chatbot… Autonomous robots… Or anything you’re likely hearing about. It has to do with a brand-new “light-speed” device turning AI as we know it into “Accelerated AI”… Making it 100 times faster… And 100 times more energy efficient — right here, on Earth. Already, some of the biggest tech investors like Elon Musk, Mark Zuckerberg, Cathie Wood, and Bill Gates are moving money into it. Just to name a few… They’re all moving money to prepare for what’s coming. But you won’t hear anything about it in the mainstream news… In fact, TV pundits spent most of this past year talking about AI worries and its “existential risk” to jobs… Or arguing whether we’re in an AI bubble and when it would pop… That’s why most Americans won’t see it coming until it’s too late. Don’t be one of them… Because if you’re holding the wrong AI stocks when “Accelerated AI” goes mainstream… You could spend the next decade just trying to claw back to even… But if you make the one move Jason reveals in this urgent video message… The next 12 to 24 months could hand you bigger gains than the entire AI boom of the last three years. Click here to hear the full story and get ahead of the crowd. But hurry, because this opportunity won’t stay hidden much longer. We have so much to look forward to, Jeff Brown
Founder & CEO, Brownstone Research P.S. Jason also shares details on 10 popular AI stocks he says you must dump before this shift goes mainstream. Names sitting in millions of 401(k)s, IRAs, and brokerage accounts. Click here to see if yours made the list.
Special Report
Darden Restaurants Serves Up Fresh Catalysts for a Stock Price RallyAuthor: Thomas Hughes. Published: 9/26/2026. 
Key Points
- Darden Restaurants delivered positive same-restaurant sales across every segment in fiscal Q1 2027 while reaffirming its full-year earnings outlook.
- Darden Restaurants continues to return significant cash to shareholders through a $1.62 quarterly dividend and aggressive share repurchases.
- Darden Restaurants’ post-earnings pullback comes as analysts remain broadly positive, and its long-term stock-price uptrend remains intact.
- Special Report: Major Buy Alert Issued for October 31st
Darden Restaurants’ (NYSE: DRI)late-September post-earnings release price pullback could be a sell-the-news, buy-the-dip event because the company’s strengths were already expected. Investors should focus on those strengths: a portfolio of well-known, market-leading brands in key categories, including niche fine dining, which is about as good as it gets. Tepid results don’t necessarily mean weak results when analysts forecast industry-leading growth and sufficient profitability to sustain financial health, capital returns, and the uptrend in stock prices. As always, the brand, management and results influence stock-price valuation and outlook, but cash flow and capital returns drive them. In this case, capital returns include dividends and buybacks, providing significant leverage even with shares trading near record levels. Darden’s dividend annualizes to about 3.1%, and aggressive share buybacks compound that return. Trailing-12-month (TTM) activity reduced the share count by 2.7% as of Q1 fiscal year 2027 (FY2027).
The net result is that cash flow, aided by a reduced share count, enables aggressive annual increases that could continue into the coming year. As it stands, Darden’s distribution compound annual growth rate (CAGR) is a moderately high double-digit figure, well above inflation. Darden’s Balance Sheet Supports Capital ReturnsDarden Restaurants’ high yield and aggressive buybacks might be red flags, but they aren’t. While higher yields and sudden share-count reductions often lead to stalled or declining returns, Darden is well-positioned to sustain its payouts and increase them in the coming year. The worst news is that equity declined 6% in Q1 FY2027, but the share-count reduction and dividend payment offset that decline. Key details include flat cash, higher current and total assets, persistently low leverage and ample cash flow. Coverage matters, and cash flow covered Q1 FY2027 activity, including capital returns and investments in store count and technology. Institutions and analysts reflect strong conviction in this investment thesis. The institutional group owns more than 90% of the stock and has been aggressively accumulating shares, with analysts expecting it to reach fresh peaks. MarketBeat’s data shows institutions buying on balance for 10 consecutive quarters, averaging a $2.8-to-$1 pace over the TTM period and ramping up activity into early calendar Q3 as analyst trends strengthened. The 27 analysts MarketBeat tracks rate the stock a Moderate Buy, with an average price target of $232.09. Consensus forecasts only modest upside as of late September, but the trend is positive, pushing the stock toward the high end of its range and fresh all-time highs. With analysts having lifted targets and ratings just ahead of the report, the trend is likely to continue in calendar Q4 if operating trends remain strong. Darden’s Q1 Results Show Steady Growth, Not WeaknessDarden’s Q1 FY2027 results and guidance update was tepid compared with analysts’ expectations, but it was no less strong for that reason. Revenue grew 5.1% to $3.2 billion, slightly below forecasts, on a 3.1% systemwide comparable-sales increase and a 2.4% increase in store count. All segments reported positive comparable sales, led by LongHorn Steakhouse’s 6.2% gain. Margin is another area of hidden strength. The company faced margin pressure but offset it to some degree, enabling better-than-expected bottom-line results. Key details include $279 million in cash from operations and adjusted earnings per share of $2.05, which met expectations despite the slight top-line miss. Looking ahead, the company expects steadiness, which is good enough, and affirmed its guidance for 3.1% revenue growth. Darden’s Uptrend Holds Despite Near-Term RisksAmong Darden’s risks are higher interest rates and their impact on costs and consumers. Higher rates can increase costs while reducing consumers’ discretionary dollars and, by extension, Darden’s revenue-generating capacity. Catalysts include closing Bahama Breeze locations and converting them to higher-yielding formats. This creates upfront cost pressure but also an opportunity to drive growth, comparable-store strength and cash flow. Stock price action is mixed after the release. The market is pulling back and may deepen the correction, potentially falling to $200 or lower before finding solid support. Even so, the stock price uptrend remains intact, and institutional investors might view the pullback as a buying opportunity. The question is how soon a rebound may form, and the answer is likely to be soon. Near-term pressures aside, consumers remain resilient, and forecasters expect some strength this holiday season. Retail sales, an indicator of consumer habits, are expected to increase by nearly 5% on average, with restaurants a potential beneficiary of the increased traffic. Investors often get Olive Garden wrong: its slower growth isn’t an issue because it remains a pillar of the company’s cash-generating power. Additionally, its size and scale enable supply-chain efficiencies, including purchasing power, that many restaurants lack. That combination of brand strength, scale and dependable cash generation helps support Darden’s broader growth and capital-return story even when quarterly results are less exciting. 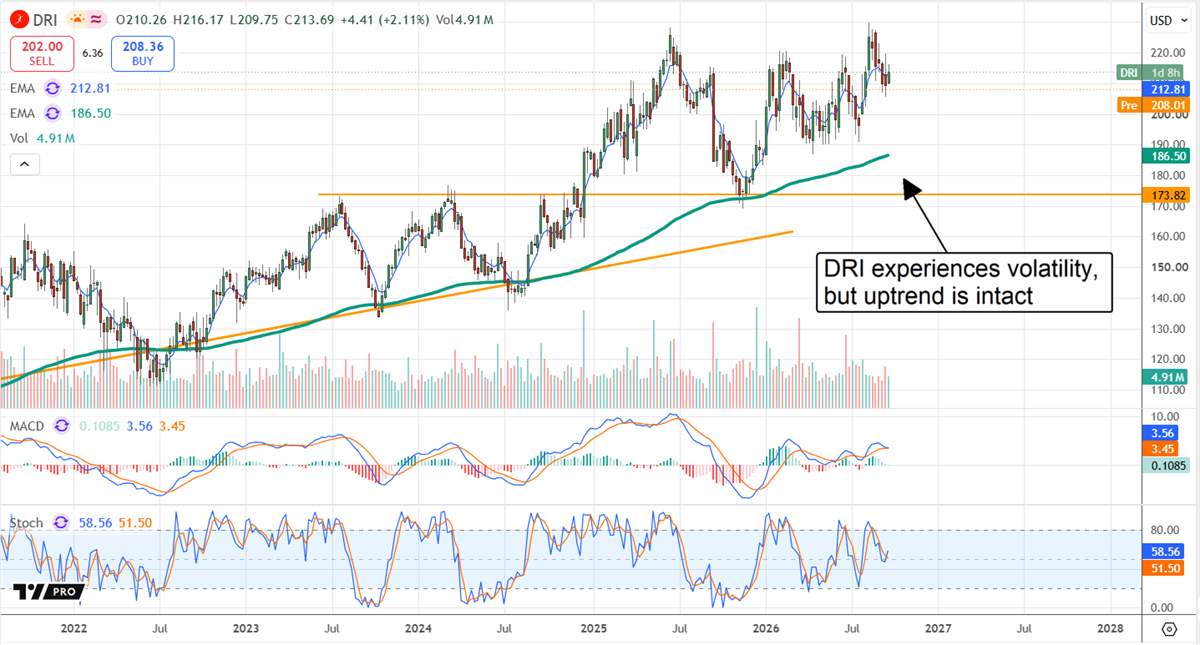
. |


0 Comments:
Post a Comment
<< Home