 A Message From Profits Run If you still haven't downloaded my "Safe Trade Options Formula" book... ...please take a few seconds and download it right now before your new temporary download link expires. I eventually plan to charge for this book, so do yourself a favor and download it now... That way, no matter how much it is in the future, you'll have a copy on your computer already. Make sense? FREE: Safe Trade Options Formula << Download Now Good Trading,
Bill Poulos p.s. Go here to save a copy of my "Safe Trade Options Formula" book to your computer before I start charging for it.
Just For You
Ride-Share Reckoning: Tesla Drives Into Uber's LaneSubmitted by Jeffrey Neal Johnson. Article Published: 9/7/2026. 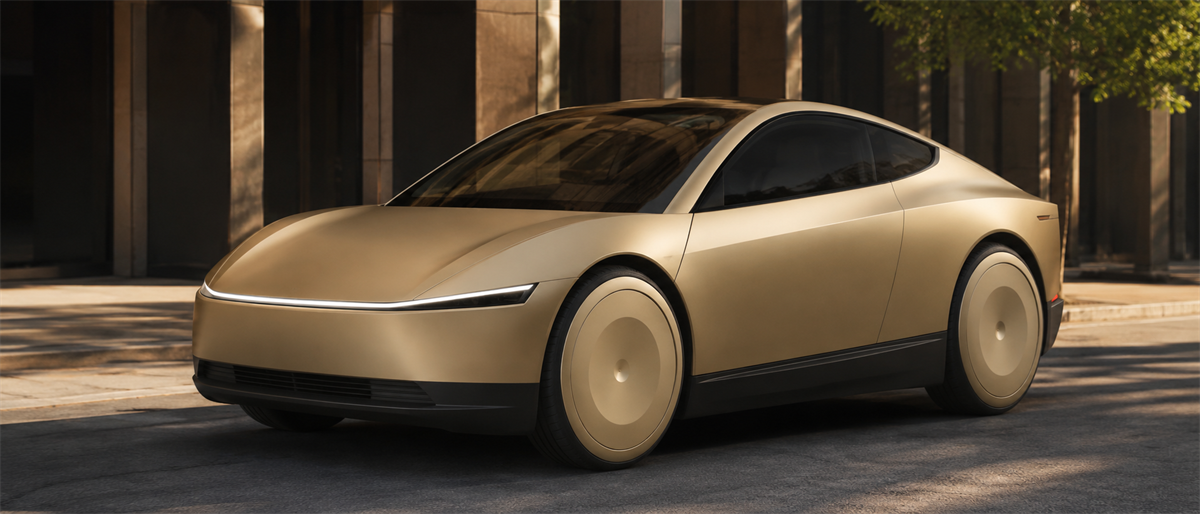
Key Points
- Tesla trades at a trailing price-to-earnings ratio near 326 as investors price in future robotaxi software revenue rather than current hardware margins.
- Uber trades at a discounted trailing price-to-earnings ratio of about 17 despite stronger net margins, reflecting market concern over driverless competition.
- Regulatory progress, including French testing of about 195,000 kilometers with no incidents, remains a key bottleneck for scaling autonomous fleet revenue.
- Special Report: A US Gold Explorer Approaches a Key Drilling Milestone
Evaluating the electric vehicle and autonomous transportation sectors requires looking beyond traditional metrics such as vehicles produced and delivered. Wall Street is increasingly focused on recurring software revenue and fleet utilization. The shift away from consumer retail sales toward commercial robotaxi fleets is changing the sector's underlying fundamentals. Understanding this dynamic helps clarify the aggressive growth multiples assigned to autonomous innovators and the discounted valuations given to legacy rideshare companies. The recent deployment of steering-wheel-free vehicles in Austin signals a structural shift in how automotive technology is valued, bringing execution risks and regulatory timelines to the forefront. Driving Margins: The Cybercab Software Pivot
This recent rollout of steering-wheel-free vehicles in Texas marks a necessary evolution for Tesla, Inc. (NASDAQ: TSLA). For years, Tesla operated primarily as a traditional hardware manufacturer, relying on direct-to-consumer vehicle sales to drive top-line revenue. That model is currently facing margin compression across the industry. Recent financial data show Tesla operating with a net margin of around 3.6% and a return on equity of nearly 3.8%. These metrics highlight the operational strain inherent in building and selling physical hardware in a highly competitive, capital-intensive environment. The recent downgrade of Tesla's financial health to TradeSmith's Yellow zone emphasizes the short-term capital pressure required to scale new infrastructure. The Austin launch is not just a product reveal; it is the physical deployment of a business model designed to unlock high-margin fleet revenue. A commercial robotaxi network would replace one-time hardware sales with continuous software monetization and utilization fees. If successful, this ecosystem would fundamentally change Tesla's cash flow profile, shifting it closer to a software-as-a-service model. The physical vehicle essentially becomes the delivery mechanism for proprietary software, allowing Tesla to capture ongoing revenue for every mile driven rather than recognizing a single transaction at the point of sale. The capital expenditures required for autonomous-driving technology are substantial, yet the potential recurring revenue base offers a clear path out of the low-margin manufacturing cycle. Valuation Traffic Jam: Pricing the Software PremiumUnderstanding this shift requires a close look at current market multiples and what they imply for future earnings. Tesla currently trades at a trailing price-to-earnings ratio near 326, with a forward price-to-earnings ratio approaching 400. To justify that premium, the market expects Tesla to significantly disrupt the traditional logistics sector. Forward earnings growth projections of around 56% suggest institutional models are looking past recent earnings misses, including the second-quarter 2026 report, in which Tesla reported approximately 33 cents per share versus the 50-cent estimate. The market is aggressively pricing in future cash flows from the autonomous network. We can use Uber Technologies, Inc. (NYSE: UBER) as a benchmark for how the market values legacy rideshare models. Uber operates with a net margin approaching 17% and a return on equity of more than 43%. Despite these solid fundamentals, Uber trades at a stagnant trailing price-to-earnings ratio of about 17. The market heavily discounts the longevity of traditional rideshare models, recognizing the existential threat posed by scalable, driverless competitors. While Uber has spent years perfecting the logistics of human-driven fleets, the structural costs of contractor payouts limit long-term margin expansion relative to a fully autonomous network. Incumbents are well aware of this dynamic and are actively positioning themselves defensively. Uber recently launched a supervised autonomous ride-hailing service in London, using Wayve's artificial intelligence technology in a fleet of Ford Mustang Mach-E vehicles. Alongside this rollout, Uber initiated a 10% reduction in its global workforce, eliminating around 3,400 jobs. These actions represent a rapid, sector-wide restructuring aimed at optimizing margins and insulating current operations from emerging automated competitors. Uber's decision to pursue third-party autonomous partnerships while simultaneously trimming headcount underscores the severity of the threat. Clearing the Intersection: FSD Testing Gains TractionWhile Tesla's premium forward multiples reflect strong institutional belief in this transition, realizing sustainable fleet revenue remains tied to operational execution and regulatory frameworks. The transition to a driverless economy is far from complete. Removing traditional controls from a vehicle introduces significant legislative hurdles that have yet to be cleared globally. Scaling an autonomous network requires continued capital expenditures on artificial intelligence infrastructure, which will pressure free cash flow until the network is fully operational and generating reliable daily fares. There are early signs of regulatory momentum abroad. French regulators recently confirmed on-road testing of full self-driving systems. Documentation submitted for European approval indicates approximately 195,000 kilometers of testing on French roads without notable incidents. This data provides evidence that regulatory tailwinds may be forming and could inform a broader European Union approval vote in the near future. Breaking through European bureaucracy would validate the safety profile of the underlying software and provide a blueprint for expansion into other highly regulated markets. However, domestic and international legislative hurdles remain the primary bottleneck to scalable fleet monetization. Building the operational logistics of fleet management from the ground up requires flawless execution. Tesla must prove it can handle the granular details of fleet maintenance, charging logistics and customer service at scale. The established logistics networks of legacy rideshare companies provide a functional, revenue-generating bridge to autonomy that pure-play entrants still need to build from scratch. The Final Mile: Capitalizing on the Driverless ShiftThe deployment of autonomous hardware represents a critical juncture in the transportation sector. Transitioning from a hardware-centric manufacturing model to a scalable logistics network offers a path to margin expansion, provided the technology and regulatory approvals align. The market is currently pricing in a successful transition for autonomous pioneers while applying a heavy discount to traditional rideshare models, forcing industry-wide restructuring and strategic partnerships. The valuation gap between innovators and incumbents reflects a clear expectation of cash flow disruption over the next decade. Investors evaluating this space might monitor the progress of international regulatory approvals and the rollout of these initial autonomous fleets. Cautious investors may prefer to watch how early fleet-utilization metrics affect quarterly cash flows before taking a position, as the premium multiples require nearly flawless execution in the quarters ahead. Observing how traditional platforms adapt their cost structures in response to these emerging networks will also provide critical context for the longevity of legacy rideshare equities. . |


0 Comments:
Post a Comment
<< Home