 A Message From Stansberry Research Analyst nicknamed "The Prophet" issues new warning for America 
Whitney Tilson shocked the nation on 60 Minutes when he accused a major company of poisoning its customers. The investigation won an Emmy and the stock fell nearly 80%. (He also called the housing crisis and the collapse of Bear Stearns and Lehman Brothers). Now, he's releasing his next big story. He says the day after our upcoming midterm elections, America will enter a period of economic change unlike anything we've seen in decades. And most investors are unprepared for what's coming. For the full presentation, go here.
More Reading from MarketBeat.com
3 Under-the-Radar Defense Stocks With Record BacklogsAuthored by Dan Schmidt. First Published: 9/7/2026. 
Key Points
- ATI, Astronics, and Ducommun each reported record backlogs in their latest earnings, but analysts caution that backlogs do not guarantee future profits.
- ATI stands out for pricing power through its hafnium and zirconium supply niche, expecting to deliver 70% of its $4.4 billion backlog within a year.
- Ducommun's record backlog masks decelerating guidance, while Astronics shows strong growth but carries high leverage with a 1.57 debt-to-equity ratio.
- Special Report: Three stocks I’m putting my money behind now
Life has two constants: death and taxes. But if you were to add a third, it might be the U.S. military’s steadily expanding annual budget. Now that the war in Iran has drastically depleted the coffers, the U.S. military is once again seeking more firepower. The Pentagon is requesting $1.1 trillion in discretionary spending for fiscal 2027, including a 188% increase in funds for missile procurement. This spending typically flows into the aerospace industry, but not evenly. Today, we’ll look beyond the prime contractors such as Lockheed Martin Inc. (NYSE: LMT) and RTX Inc. (NYSE: RTX) to three lesser-known defense stocks. Each company posted a record backlog in its most recent earnings report, but record backlogs don’t always translate into record profits. We’ll examine the numbers to determine which company is best positioned to monetize its growing order book. ATI: Specialty Materials Producer With Pricing Power
Allegheny Technologies Incorporated, better known as ATI Inc. (NYSE: ATI), is the largest company on our list, with a $27.8 billion market capitalization and more than $4.5 billion in trailing 12-month sales. Much of the company’s recent growth has come from transforming its Flat Rolled Products segment into Advanced Alloys and Solutions (AA&S). Flat Rolled Products was a cyclical industrial segment that produced steel, nickel and plate-metal products. But AA&S has become a crucial defense supplier, and aerospace now accounts for more than 44% of segment revenue, according to the company’s Q2 2026 numbers. ATI has built its niche around hafnium and zirconium, two minerals that only a handful of firms worldwide can produce to aerospace and military standards. Defense demand has been strong enough that the company has deliberately withdrawn capacity from other segments and reallocated it to defense orders with nearer delivery dates. ATI expects to deliver 70% of its record $4.4 billion backlog within the next 12 months. Management believes AA&S margins are sustainable in the mid-20% range, giving the company pricing power that the other two stocks on our list can’t match. 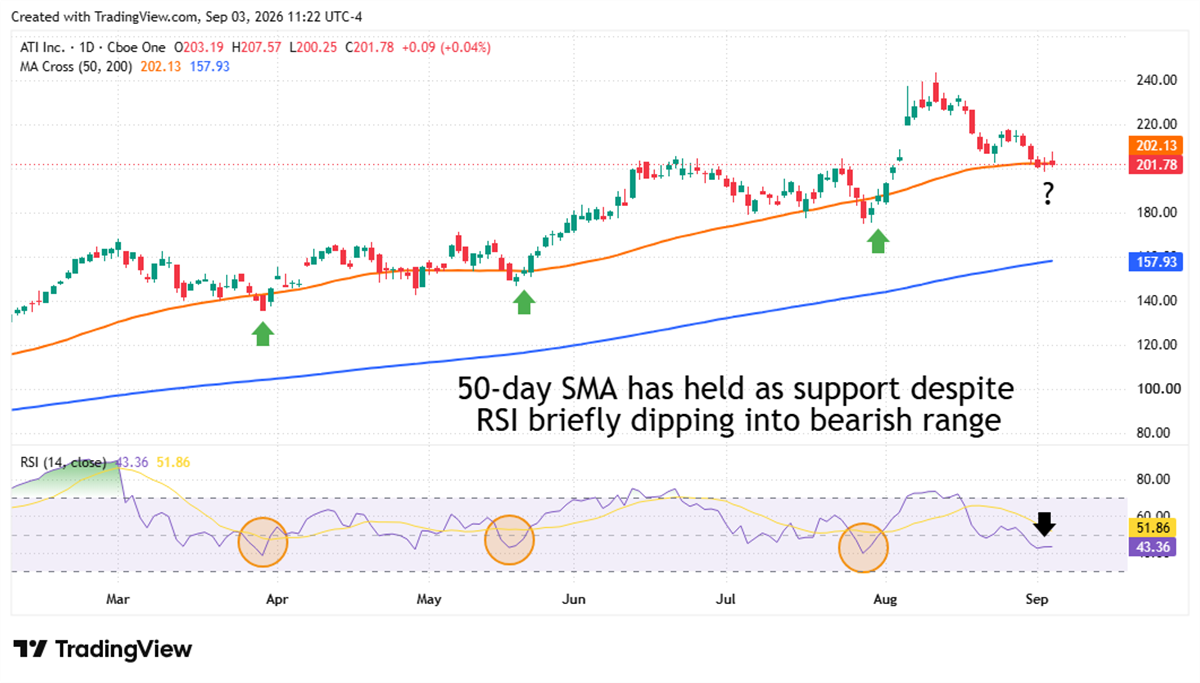
ATI also has the cleanest chart of the three stocks, with strong support along the 50-day moving average (MA) and a Relative Strength Index (RSI) that rarely stays below 50 for long. Shares are testing the 50-day MA again, creating another potential inflection point. The moving average has provided a good entry point for investors on the past three occasions. Astronics: Cleanest Defense Link But Highest LeverageIf you want to increase the risk-reward profile of your mid-cap defense stocks, Astronics Corp. (NASDAQ: ATRO) offers significant leverage. The company recorded less than $950 million in sales over the last 12 months, but its rapid growth in onboard flight hardware and components has driven the stock up more than 65% year to date (YTD). Astronics reported $260 million in revenue during its Q2 2026 earnings call, with more than $237 million coming from the Aerospace segment. Total revenue increased 27% year over year (YOY), book-to-bill was 1.18, and the backlog reached a record $780 million, with the bulk once again devoted to Aerospace. But this growth has been funded by debt, and the company’s debt-to-equity ratio is 1.57, indicating significant leverage. Astronics needs to keep growing to support its valuation, and any slowdown in revenue or bookings could trigger a sharp re-rating. 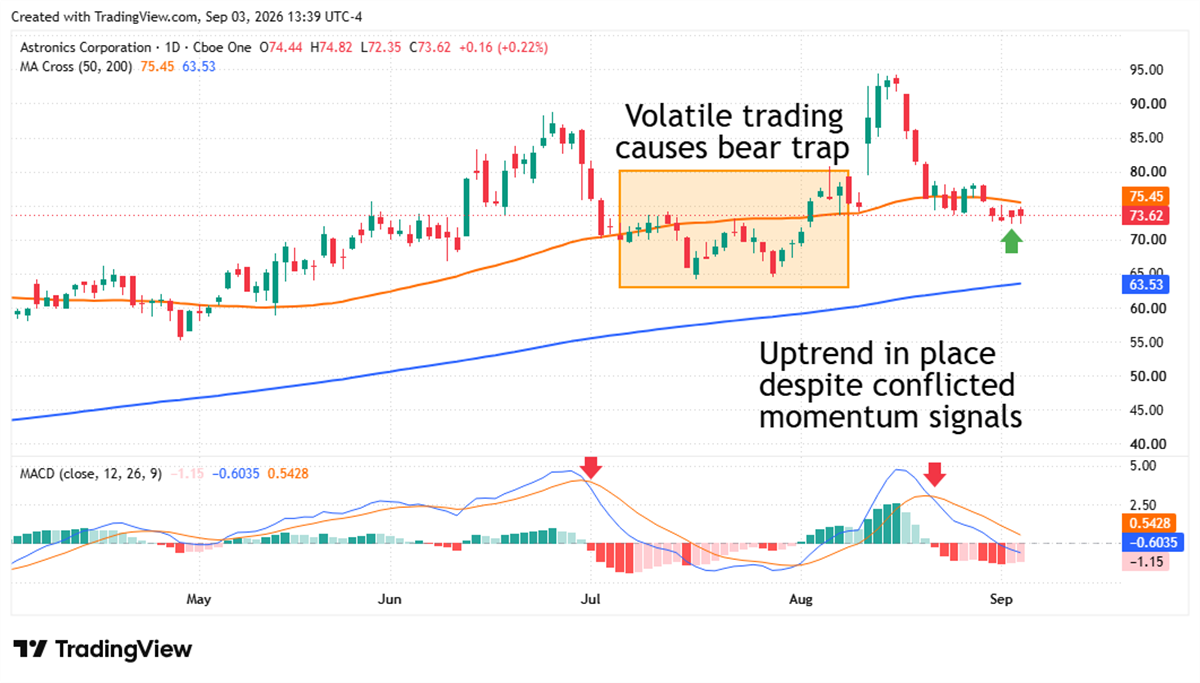
ATRO shares have a beta of 1.20, meaning the stock is 20% more volatile than the broader S&P 500 index. High-beta stocks often produce false technical signals, as we saw in July when the stock dipped below the 50-day moving average after a bearish cross on the Moving Average Convergence Divergence (MACD) indicator. Day and swing traders may find stocks like ATRO more enticing, but the long-term trend is still pointing higher. The company also recently guided for its first-ever $1 billion sales year. Ducommun: Strongest Backlog Masks Guidance DecelerationDucommun Inc. (NYSE: DCO) is a prime example of why headline backlog numbers require further scrutiny. Backlogs and order books are leading indicators because they reflect bookings from future customers rather than revenue the company has already realized. But backlogs leave a lot to the imagination: They don’t tell us the quality of the orders, how long they will take to complete or what margin the company can charge for future business. Ducommun, a $2.5 billion electronic systems manufacturer by market capitalization, has the strongest backlog optics of the three stocks on today’s list. Its quarterly book-to-bill rate of 1.4 is also higher than Astronics’ rate; ATI does not report book-to-bill. The company has $1.16 billion in remaining performance obligations, but management’s guidance during the fiscal Q2 2026 earnings release dampened the headline numbers. Q2 revenue rose 12% YOY to a record $224.5 million, missile revenue increased 68% during the period, and gross margins expanded to a company record of 28%. But then came the guidance: Management reiterated its previous-quarter figures, calling for high-single-digit growth in fiscal 2026 but low-single-digit growth in Q3 and Q4 because of commercial destocking and aerospace production being pulled forward. The order book might be growing quickly, but Ducommun doesn’t expect to convert those orders into revenue before the end of the fiscal year. Meanwhile, the missile program continues to do the heavy lifting, while the space, radar and naval platforms segments all declined in Q2. 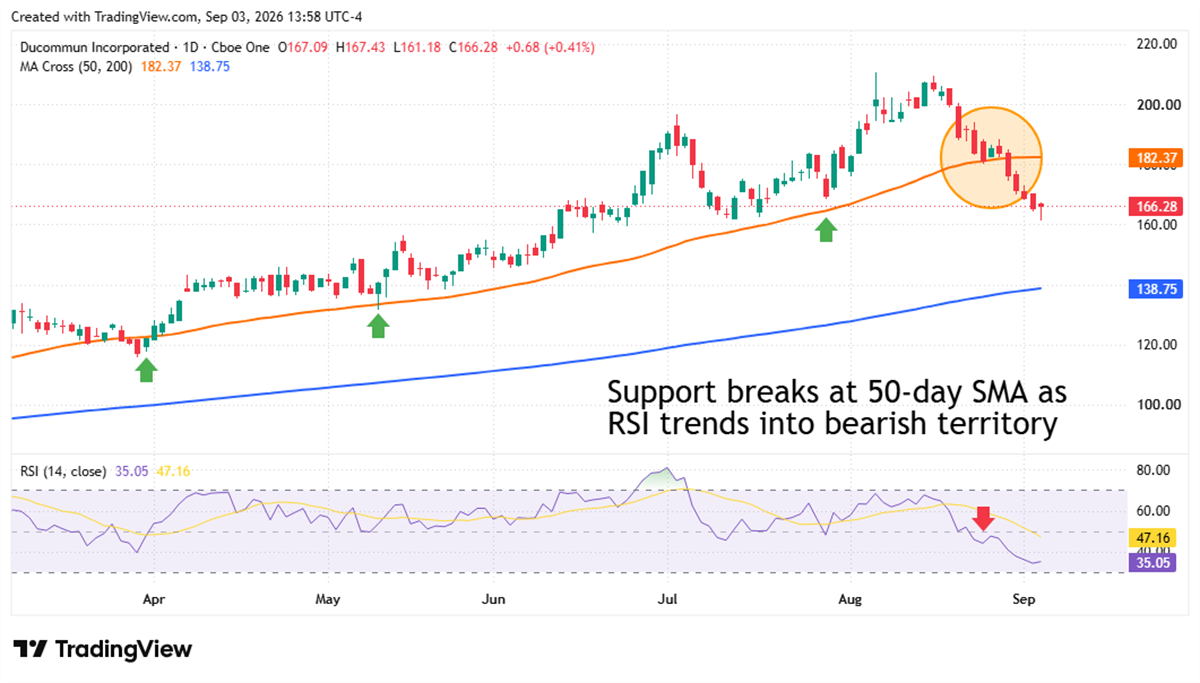
DCO shares are still up more than 70% YTD, but post-earnings profit-taking now risks turning into a full-fledged decline. The stock has closed lower than it opened in 11 of the last 12 trading sessions, and the 50-day moving average support level has now been broken. The RSI confirmed the downward pressure by moving below the 50 midpoint, signaling that sellers currently control the stock’s momentum. The next earnings report isn’t scheduled until Nov. 5, so investors should expect more volatility in the weeks ahead for DCO.
This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here.
This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here.
. |


0 Comments:
Post a Comment
<< Home