 A Message From The Early Bird Good day, Our research analysts are set to release their next stock idea tomorrow morning just before 12:00 PM Eastern. It will be sent first to investors that sign up to receive the Early Bird Stock of the Day via text, and the next morning to email newsletter subscribers. Don't miss your chance to be the first to see our next stock pick. Our last pick was quite popular with subscribers. This is a free service from The Early Bird and MarketBeat. If you want to take advantage of this unique buying opportunity, simply click the link below to add yourself to our distribution list. Get The Early Bird Stock of the Day The Early Bird Team
Special Report
Insiders Signal Deep Value In DICK’s Sporting GoodsReported by Thomas Hughes. First Published: 9/21/2026. 
Key Points
- Insider buying has picked up sharply after DICK’s Sporting Goods’ post-earnings sell-off, offering a notable counterpoint to weaker guidance and Foot Locker concerns.
- The longer-term opportunity increasingly depends on whether DICK’s can use its technology, customer data and retail ecosystem to extract more value from Foot Locker.
- Analyst caution and near-term margin pressure remain significant hurdles, but the lower valuation and roughly 4% dividend yield have changed the risk-reward setup.
- Special Report: 5 Moves to Make Before Election Day [Nov 3]
Insiders are signaling deep value in DICK’s Sporting Goods (NYSE: DKS), with a handful of directors buying shares in early Q3. The purchases are notable not only because they run counter to the trend but also because they come in response to a deeply discounted share price. DKS shares imploded following the Q2 miss; however, the market appears to be mispricing the opportunity. While headwinds remain, this isn't a retail turnaround. Instead, it’s an aggressive ecosystem expansion underpinned by technology and, more importantly, a vast pool of data on athletic shopping habits and the revenue and earnings power that data can generate. The hurdle today is the shoe segment and, specifically, integrating Foot Locker and realizing its potential. The pain is store-count rationalization, compounded by consumer headwinds. The opportunity is to expand DICK’s Sporting Goods, traditionally a big-box retailer, into niche urban markets in a targeted way, providing athletes with what they’re looking for and the accessories to go with it. Foot Locker also provides real estate, making this a land grab as much as anything else, along with entry into a coveted demographic: fashionable urbanites. Additional benefits include cross-selling and omnichannel integration. Insiders and Institutions Reflect Confidence in DICK’s Long-Term Opportunity
Insider buying is noteworthy because of the timing and the individuals involved, including industry insiders and tech titans. It is also notable because they didn’t need to buy. Insiders, including family holdings, account for about 30% of the company and are reinforced by a strong institutional presence. In this scenario, insider buying can trigger market inflows and drive a reversal. Institutions likewise own a significant amount, with total holdings approaching 90%, and the group is accumulating. InsiderTrades data reveals that activity spiked to record levels in Q3 as DKS shares fell to long-term lows. Valuation is a hurdle today, but execution can overcome it. Trading at approximately 11.5x to 12x its current-year outlook, the stock aligns with long-term trends but fails to price in the forecasts. Analysts expect the DICK’s-Foot Locker integration to unlock modest but sustainable revenue growth, compounded by steadily improving margins. In this scenario, DKS shares trade at around 5x the six-year outlook, suggesting 100% upside from current levels—and that’s assuming the forecasts are correct. Assuming DICK’s progresses with its strategy and consumer headwinds ease, revenue and earnings growth could outperform estimates, setting the stage for earnings growth to amplify the valuation-based upside. If headwinds clear and the market reprices DKS to align with peers, which trade in the high-teens to high-20x range, the upside potential more than doubles. Analysts Send DICK’s to Long-Term Lows: Can Keep Price Depressed in 2026Analysts present another hurdle for share prices, as trends reflect caution through numerous downgrades and price-target reductions following the Q2 release. That caution is reflected in the consensus rating: Hold across 23 analysts, with 11 Buy, nine Hold and three Sell ratings. While low-end targets put DKS in the $100 to $110 range, the consensus is closer to $167, aligning with the midpoint of a trading range and representing more than 35% upside from the critical support target. The likely outcome is that DKS reverts to the middle of its range; the only questions are when and what comes next. 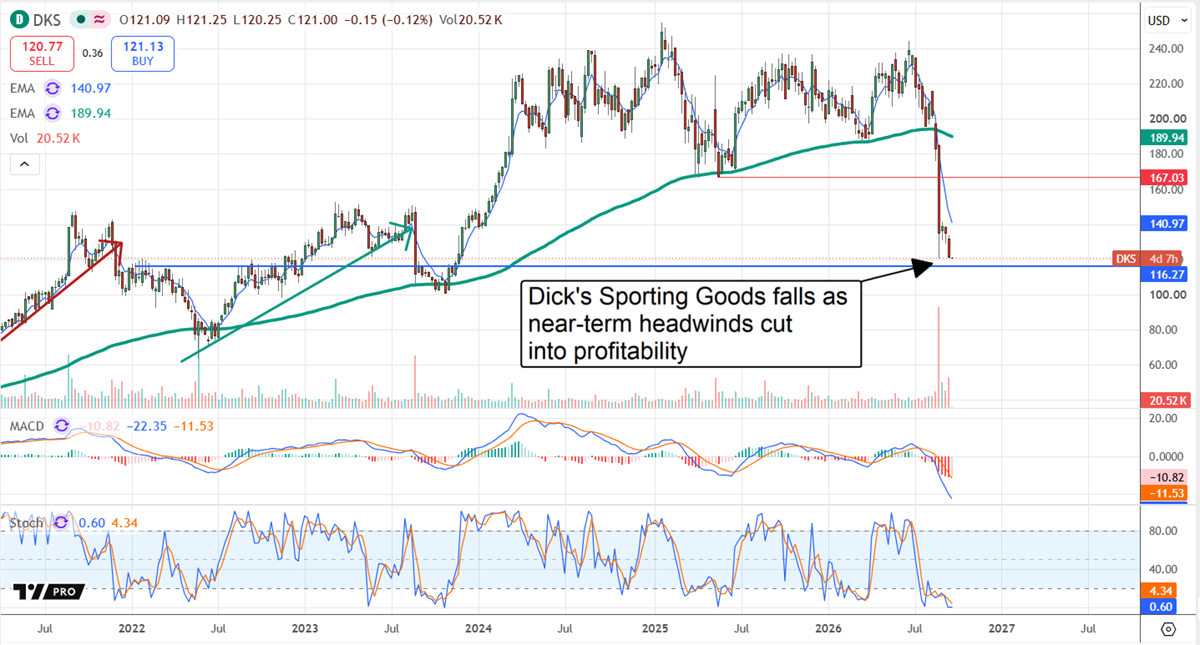
Critical support is just above $115. The technical risk is that DKS's initial bounce was very weak despite the high volume, suggesting that a dead-cat bounce may be in play. The term assumes that even a dead cat will bounce if it hits the ground hard enough, and such a move can lead to lower prices or stagnation. Lower lows aren’t expected, given that results missed expectations but weren’t bad and still offer opportunities for growth, margin improvement and sustained capital returns. Stagnation is a real risk, however; DKS shares can languish at these lows indefinitely if upcoming results don’t reinvigorate market appetite. DICK’s dividend is substantial, yielding approximately 4% with shares at mid-September lows. The payout is reliable but carries some risk, as margin pressure remains and free cash flow hasn’t been sufficient. The likely outcome is that dividend growth slows in the coming year but doesn’t disappear before accelerating the following year. The more pressing concern is the impact on share buybacks, which have slowed, and the share count, which has increased. The caveat is that the increase in the share count is tied to the Foot Locker acquisition, while buybacks, albeit at a slower pace, continue to reduce the share count each quarter. DICK’s Q4 results are likely to be a catalyst. The company expects meaningful comparable-sales improvements as early as Q4, with structural margin recovery beginning in early 2027 and progressing throughout the year as restructuring concludes. Analysts forecast another quarter of solid growth, offset by margin pressure. . |


0 Comments:
Post a Comment
<< Home