 Right now, you can buy a dollar's worth of gold for about 36 cents. That sounds impossible. Here's how it's real. The major gold miners are throwing off record cash flow — even after gold's recent pullback. The four largest have never had this much free cash on hand. Ever. At today's gold price, they're running margins as high as 75% — the most profitable they have ever been. Which hands them a problem. Go here to see the problem — and why the majors are about to go on a shopping spree for the ages. When a major gold miner makes record profits, it does one of two things: hand the cash back to shareholders, or buy the best junior mining assets to secure future production. And here's the piece the market is missing: The best junior assets are still priced as if gold were stuck at $1,800 an ounce — not north of $4,000, where it trades today. So the majors are staring at their own future production shrinking, sitting on record cash, looking at top-tier junior assets trading at a fraction of what that gold is worth at today's price. They don't have a choice. They buy — or their output keeps shrinking until they're out of business. That's how you buy a dollar of gold for 36 cents: you own the junior before the major is forced to pay up for it. The gap between what these assets are worth and what they trade for has a name. I call it the Golden Anomaly. It only appears early in a gold bull market, and it closes fast — usually the moment the majors start writing cheques. So you can pay full price after the gap closes… Or buy the dollar for 36 cents while the Anomaly still exists. My name is Garrett Goggin, CFA, CMT, and it's why Porter Stansberry recently called me: "THE most knowledgeable gold investor in the world." Go here to see my Golden Anomaly portfolio — and the three names next on the majors' shopping list. Best, Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio
This Week's Bonus Content
OneSpaWorld Keeps Turning Cruise Demand Into Record EarningsWritten by Peter Frank. Article Published: 8/16/2026. 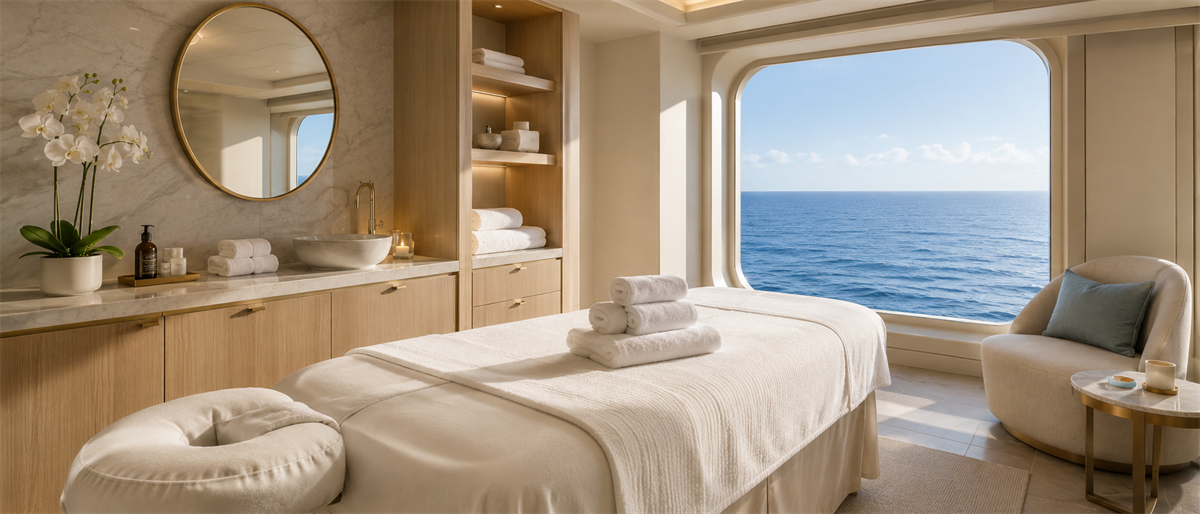
Key Points
- OneSpaWorld has posted 21 consecutive quarters of record revenue and adjusted earnings, with second-quarter revenue rising 9% to $261.2 million.
- Analysts maintain an overall Buy rating on the stock, with an average price target of $30.60 implying about 15% upside from current levels.
- The company's heavy reliance on revenue-sharing deals with cruise operators poses a key risk, and its shares trade at a premium valuation near 33 times earnings.
- Special Report: Man who Predicted Trump 2016 Win: “Prepare for Mid-Term Meltdown”
While major cruise lines are performing well with rising passenger counts and revenue, OneSpaWorld Holdings (NASDAQ: OSW) is performing even better. In fact, every time you walk past the spa deck on one of these ships, there’s a good chance OneSpaWorld is behind the massages, facials and medi-spa treatments being offered. The Bahamas-based company has also become a favorite among analysts.
With a current Buy rating, OneSpaWorld has built its business model on decades-long revenue-sharing partnerships rather than on ships or hardware. It has now delivered 21 consecutive quarters of record revenue and adjusted earnings, a streak that includes the pandemic years. For investors, it’s a little-known company worth watching, whether its smooth sailing continues or major cruise operators change course. Record Growth ContinuesThe company’s latest report, released July 29, continued that story. Although the results were not exactly blowout numbers, they extended a streak that is difficult to find in the consumer services industry. For the second quarter, OneSpaWorld reported that total revenue rose 9% year over year to $261.2 million, a quarterly record and a result that topped analysts’ expectations. Net income jumped 16% to $23.2 million, or 23 cents per diluted share. On an adjusted basis, earnings came in at $29.8 million, or 29 cents per share, edging past the 28 cents analysts had modeled and rising from 25 cents a year earlier. Adjusted earnings before interest, taxes, depreciation and amortization (EBITDA), a key profitability measure for the industry, climbed 13% to $34.4 million. First-Half Results Strengthen the OutlookThe first half of the year tells an even stronger story. Six-month revenue rose 11% to $508.9 million, while reported net income surged 27% to $44.5 million, or 44 cents per diluted share. Supported by that momentum, management raised its full-year 2026 guidance to a range of $1.018 billion to $1.038 billion in total revenue. Adjusted EBITDA is expected to reach $130 million to $140 million, implying roughly 10% growth at the midpoint. For the third quarter, the company is guiding for revenue of $268 million to $273 million and adjusted EBITDA of $35 million to $37 million. Multiple Growth Drivers Support ExpansionUnlike other cruise recovery stories, OneSpaWorld’s growth drivers help explain the company’s durable expansion. The company focuses on catering to passengers rather than spending to get them on board. It now operates health and wellness centers on 208 ships, up from 200 a year earlier, and is adding higher-margin services such as medi-spa treatments. Those services grew faster than the overall business during the quarter, although they account for less than 10% of revenue. Pre-booked services, in which guests reserve treatments before boarding, rose 14% during the period. Forward bookings across the fleet are running 20% ahead of last year, a leading indicator that demand remains strong. The company is also betting on artificial intelligence to generate more revenue and improve efficiency. It has implemented an internal tool called Amanda across 188 vessels to help optimize scheduling and upsell services. OneSpaWorld said its virtual assistant, Ava, resolved 96% of internal support requests without human intervention. Analysts Remain Bullish on the StockAnalysts clearly like what they see. With an overall Buy rating, the company’s shares carry one Strong Buy rating, five Buy ratings and one Hold rating. The average 12-month price target now stands at $30.60, implying about 15% upside from current levels. The highest price target is $35 per share, while the lowest is $28, suggesting analysts do not expect a significant swing in either direction. Indeed, wild swings are rare. With shares trading around $26.60, the stock is up about 28% so far this year. The stock’s recent pullback appears to be linked in part to a wave of insider selling. However, during the second quarter, BlackRock reportedly opened a $278 million position in the company, while several other funds also bought shares. Cruise Industry Dependence Remains a Key RiskPerhaps the biggest risk is the company’s concentration. Nearly all of OneSpaWorld’s revenue flows through long-term, revenue-sharing agreements with major cruise operators. Any significant disruption or broader downturn in the cruise industry could hit the business disproportionately hard. For investors seeking income, OneSpaWorld pays only a quarterly dividend of 5 cents, translating to a yield of roughly 0.8%. As more of a growth stock with a price-to-earnings ratio of about 33, the company’s premium valuation could also come under pressure if the industry suffers a serious setback. Strong Execution Comes With a Premium ValuationFor investors, the question is less about the company itself and more about the industry in which it operates. With no serious waves in sight, OneSpaWorld is executing well in a niche that is easily overlooked. Its revenue and earnings growth, combined with the potential for greater AI-driven efficiency, could keep the stock on growth investors’ watchlists. However, with a market capitalization of only $2.7 billion and a business that depends on a single industry, its valuation leaves little room for disappointment. If the cruise industry maintains its momentum, OneSpaWorld could be a strong way to tap into a captive segment that appears ready to spend. . |


0 Comments:
Post a Comment
<< Home