A Message From Brownstone Research Editor’s Note: Jeff Brown is the former tech executive who picked Nvidia in 2016 before it jumped 37,000% higher. He’s now recommending another AI stock that’s the same size Nvidia was 10 years ago. He calls it “Elon Musk’s One Stock Retirement Plan” because he believes Elon Musk is about to create massive demand for this company’s patented technology. Click here to see the details or read more below.
Dear Reader, Sometimes you come across an opportunity so explosive… That it has the potential to turn a small stake… Into a six figure and in some rare cases even a seven-figure nest egg… Like it happened when I picked Nvidia in 2016. It jumped high enough to turn $5,000 into an entire retirement nest egg of $1,895,000. And while I can’t guarantee you’ll become a millionaire... I think this little-known AI stock is one of those opportunities… Which is why I call it “Elon Musk’s One Stock Retirement Plan.” Now, if this idea of retiring with a single stock sounds crazy to you… You should know that some of the best investors in the world believe that the idea of diversification is a little overrated. Stanley Druckenmiller said… “You don’t get rich by diversifying into 50 mediocre assets. You get rich by finding two or three asymmetric home runs.” I believe this stock is an asymmetric home run. Or listen to legendary investor Peter Lynch. He said… “I would own one stock if I can find one great stock.” Even Warren Buffett said… “Diversification is protection against ignorance. It makes little sense if you know what you are doing.” Click here now and I’ll show you why I believe this stock might be the only one you need to retire. Jeff Brown,
Founder & CEO, Brownstone Research P.S. If I could buy only one stock, this would be it… it might just be the perfect tech stock. It’s a leader in an AI breakthrough that’s protected by 150 patents… It’s a small company, unknown to most people… still in the initial phase of exponential growth… Plus, it has a near term catalyst that could send shares skyrocketing… starting November 11.
Exclusive Article from MarketBeat Media
Microsoft’s Azure Reporting Shift Adds Clarity, But the Bull Case Came FirstAuthored by Chris Markoch. Originally Published: 9/11/2026. 
Key Points
- Microsoft will reorganize its financial reporting into two segments in fiscal 2027 while providing quarterly revenue figures for Azure and other key businesses.
- Microsoft’s new disclosures should give investors a clearer view of AI monetization, but they do not change the company’s overall revenue or expense guidance.
- Analyst ratings, price targets, and institutional buying patterns remained largely unchanged around the announcement, suggesting Wall Street had already priced in bullish expectations before the reporting change.
- Special Report: The REAL Reason Trump is Invading Iran
A company’s quarterly 8-K filing is typically a pro forma document. In other words, there’s usually nothing in it to excite investors one way or another. But the Q4 2026 8-K from Microsoft Corporation (NASDAQ: MSFT) included a detail that adds context to the stock’s powerful post-earnings rally. Specifically, the company said that, beginning in fiscal 2027, which started July 1, 2026, it would overhaul its financial reporting structure. Since 2015, Microsoft has reported three business segments: Productivity and Business Processes, Intelligent Cloud, and More Personal Computing.
Beginning in fiscal 2027, that number will drop to two: Agents and Infra and Devices and Consumer. According to Microsoft, the new structure will better reflect how the company operates and allocates resources as artificial intelligence (AI) becomes a more significant part of its business. Microsoft's Azure Revenue Disclosure Is the Bigger StoryThis change could easily be dismissed as a company dressing up its financials without adding substance for investors. That would be a mistake in this case. Microsoft Azure, its cloud computing business, has helped justify the company’s premium valuation for the past several years. Under the new structure, Microsoft will provide quarterly revenue transparency for several specific business units, including Azure and Microsoft 365 Cloud. Until now, Microsoft has disclosed Azure’s quarterly growth rate but not its quarterly revenue in dollars. In its Q4 2026 report, the company said that Azure crossed $100 billion in annual revenue for the first time. On a quarterly basis, it had disclosed only growth in percentage terms. Beginning in Q1 of fiscal 2027, Microsoft will provide quarterly revenue figures for Azure and several other key businesses, giving investors a much clearer view of the dollars flowing through its cloud infrastructure. Microsoft's New Segments Will Give Investors More AI VisibilityAzure will be part of Microsoft’s Agents and Infra segment. The segment will combine Microsoft’s enterprise applications and agents, including Microsoft 365 and GitHub. GitHub cloud services and Security Copilot will move from Azure into Microsoft 365 commercial cloud. The segment will also include productivity and server licensing, Industry Solutions, and Frontier and support services. In the Devices and Consumer segment, Microsoft will report on search and advertising, Xbox, Windows original equipment manufacturer (OEM), and devices. LinkedIn Marketing Solutions and LinkedIn Premium subscriptions will be included in the company’s search and advertising reporting. The Microsoft Stock Rally Started Before the 8-KIn and of itself, a segment overhaul is a disclosure change, not a business change. Microsoft’s total revenue, cost of revenue, and operating expense guidance are unchanged under the new structure. That distinction matters when considering the stock’s post-earnings move. Shares climbed from the low $400s in August to a fresh high above $520 in early September before settling back near $492. The rally was therefore well underway before the 8-K crossed the wire on Sept. 2. That timing raises the real question: Is the restructuring driving the stock, or is the market simply catching up to a bull case that Wall Street had already embraced? Wall Street Was Already Bullish on Microsoft StockIf the restructuring were genuinely new information, it should show up in analyst behavior. It hasn’t. MarketBeat’s Microsoft analyst ratings show that 47 analysts have covered MSFT over the past 12 months. The consensus rating of Moderate Buy includes 42 Buy ratings and five Holds. That consensus rating hasn’t moved in the last 12 months. The current consensus price target is $564.27, representing roughly 15% upside from current levels. It stood at $558.87 a month ago and $561.20 three months ago, remaining essentially flat around the announcement. Most of the bullish conviction was already in place over the summer, well before the segment news broke. Ownership data tells the same story. Institutional investors hold 71.13% of MSFT shares, according to MarketBeat’s tracking of 13F filings. Over the trailing 12 months, institutions bought roughly $326.92 billion in stock against $101.3 billion in sales, a pattern of sustained accumulation rather than a reaction to a single filing. Technical Setup Predates the Reporting ChangeThe technical setup supports the “catching up” interpretation. Microsoft’s 50-day moving average, at $449.06, sits well above its 200-day average of $431.07, confirming a golden cross that formed as the stock recovered from its April low near $350. That bullish crossover predates the 8-K by weeks. Price action since April has been a steady climb. Shares fell to a 52-week low of $349.20 before recovering through the spring and then breaking sharply higher after Microsoft’s July 29 earnings report. That post-earnings breakout, not the September news cycle, marked the real technical shift. Shares now sit at about $492, just below $500, a level that acted as resistance in October 2025 and is doing so again after the early-September push to $520 failed to hold. That looks like normal digestion after a fast move rather than a trend change, with both moving averages still rising beneath the price and offering support in the $431 to $449 range. 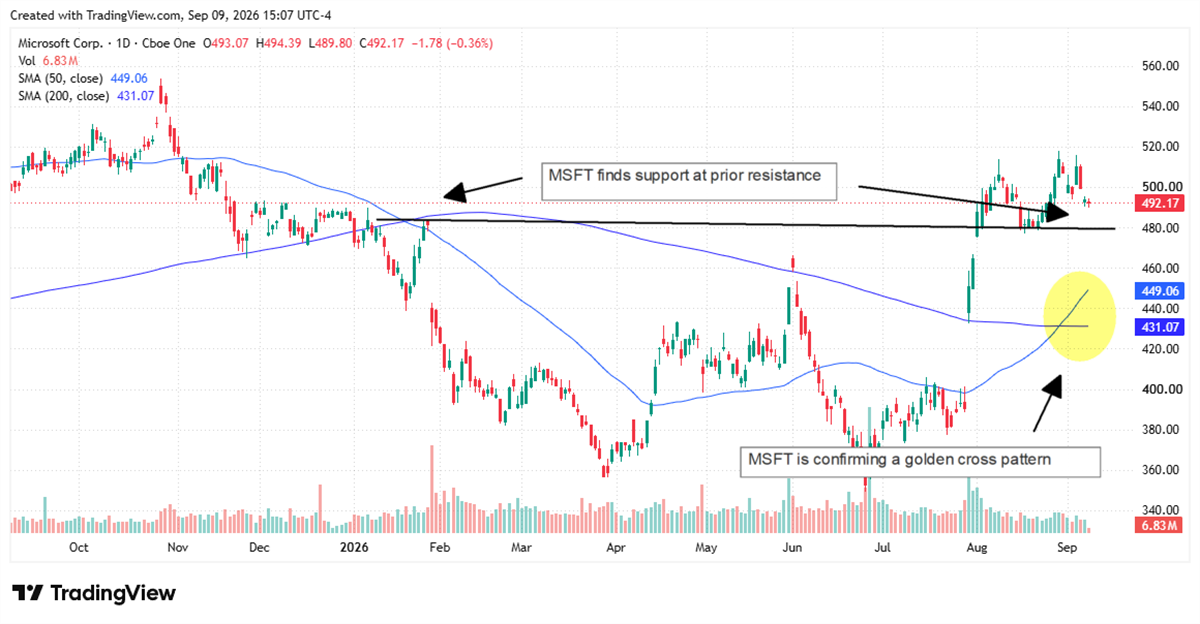
Microsoft's AI Reporting Change Adds Clarity, Not a New Bull CaseNone of this makes the restructuring meaningless. Quarterly Azure revenue disclosure is a real transparency upgrade and will shape how the market evaluates Microsoft’s AI monetization going forward. But the price action, flat analyst consensus, and steady institutional buying all point in the same direction: The market didn’t reprice Microsoft because of the filing. It had been repricing Microsoft for months, and the filing came amid a rally that was already underway. . |